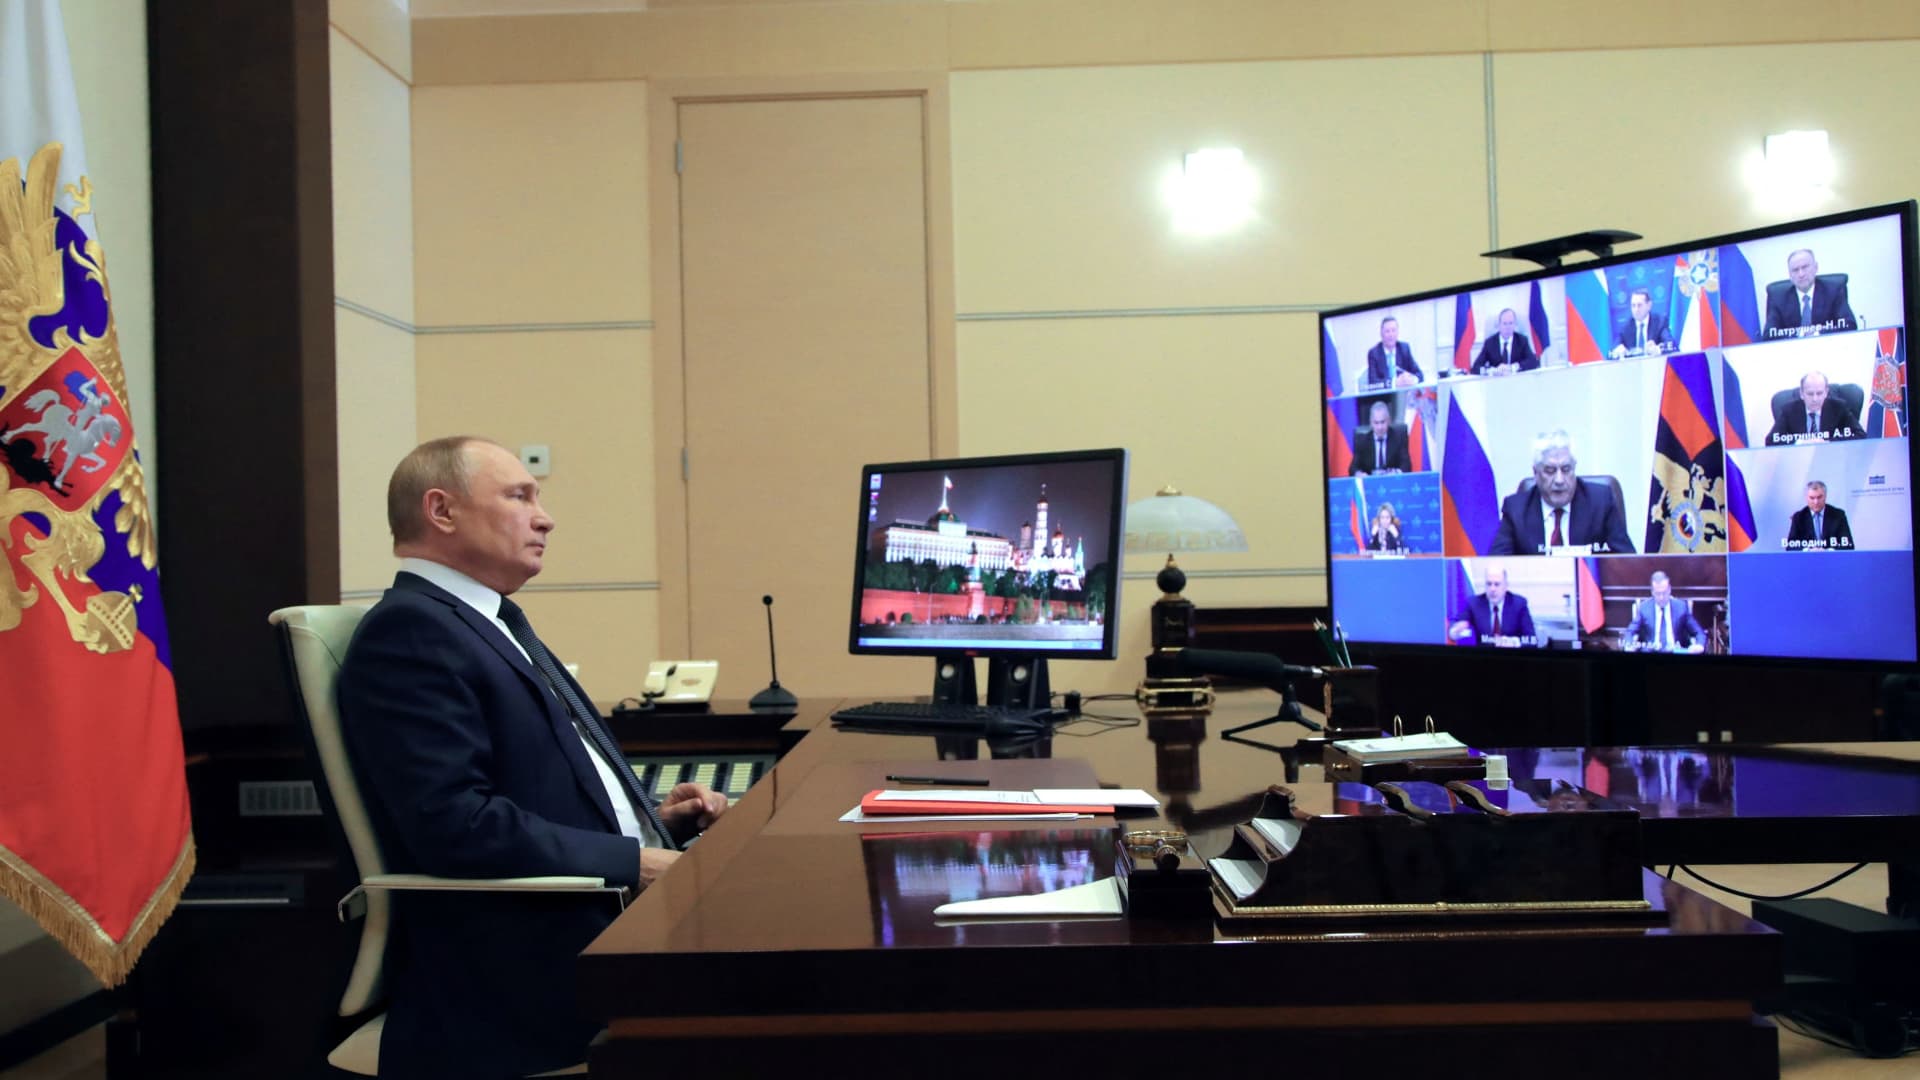
Russian President Vladimir Putin attends a meeting with members of the Security Council at a residence outside Moscow, Russia April 1, 2022.
Mikhail Klimentyev | Sputnik | Reuters
The Russian economy is set to shrink sharply this year while inflation skyrockets, as punitive international sanctions in response to its unprovoked invasion of Ukraine begin to bite.
Russian manufacturing activity in March contracted at its sharpest rate since May 2020, in the early stages of the Covid-19 pandemic, as material shortages and delivery delays weighed heavily on factories.
The S&P Global purchasing managers' index (PMI) for Russia, published on Friday, dropped from 48.6 in February to 44.1 in March, with anything below 50 representing contraction. Goldman Sachs economists noted on Friday that the fall was "broad-based, with sharp drops in the output, new orders, and (especially) the new exports orders components."
In a note Wednesday, economists at Capital Economics projected that Western sanctions are likely to push Russian gross domestic product into a 12% contraction in 2022, while inflation is expected to exceed 23% year-on-year.
The European Bank for Reconstruction and Development has projected a 10% shrinkage in the Russian economy, which would still constitute the country's deepest recession for almost 30 years, with GDP then flatlining in 2023 and entering a prolonged period of negligible growth.
Goldman Sachs has also forecast a 10% contraction, while the Institute for International Finance think tank has projected a more damaging 15% plunge in Russian GDP in 2022 and a further 3% in 2023.
Fears of a Russian sovereign debt default have not materialized, however, with the Kremlin managing to service a recent closely-watched bond payment despite the shackles of sanctions by Western powers that have frozen huge portions of the central bank's $640 billion stockpile of foreign currency reserves.
Russian stocks have also edged higher since reopening on Mar. 24 after a month-long shutdown of Moscow exchanges, along with the ruble, though capital control measures taken by the Central Bank of Russia and the fading risk of debt default are partially responsible.
"A more sustained recovery will probably require a peace deal which still looks far away. Meanwhile, spillovers from the war will be felt acutely in Central and Eastern Europe (CEE)," Capital Economics Chief Emerging Markets Economist William Jackson said in the report.
"Industry will be hit by supply disruptions and higher inflation will weigh on households' real incomes and dampen consumer spending. We expect the war to shave 1.0-1.5%-pts off growth in CEE this year."
The outlook for Russia may yet darken further following the emergence over the weekend of allegations of civilian massacres by Russian forces in Bucha and other Ukrainian towns. The alleged atrocities will push back expectations for peace talks and increase the threat of more punitive international sanctions.
Ukraine's top prosecutor said on Sunday that 410 bodies had been found in towns recaptured from retreating Russian forces around Kyiv as part of an investigation into possible war crimes, while Ukrainian President Volodymyr Zelenskyy accused Russia of genocide. Russia has denied allegations that its forces killed civilians in Bucha, 23 miles northwest of Kyiv.
The European Union plans to introduce fresh sanctions against Moscow in the wake of the new reported atrocities, with European Council President Charles Michel announcing on Twitter that "further EU sanctions & support are on their way."
British Foreign Secretary Liz Truss will travel to Poland on Monday to meet with Ukrainian and Polish counterparts ahead of talks with G-7 and NATO allies later this week, and is expected to call for tougher sanctions against Russia.
Despite the sharp declines in Russia's March PMIs, Goldman Sachs noted on Friday that activity across some CEEMEA economies was surprisingly robust, with gains in Hungary and South Africa offset by declines in Poland and the Czech Republic.
"Hungary's PMI has been relatively volatile in recent months, so we would downplay the significance of its gain (not least because our analysis suggests that it is relatively exposed to the Russia-Ukraine conflict)," Goldman economists wrote.
"For South Africa, its direct trade with Russia and Ukraine is limited, while it is benefiting from higher commodity prices."
Child care is a two-generation issue: Gaps in quality and access affect not only the education that children receive but also their parents’ ability to go to work.
The high cost and other child care factors can keep parents, especially women, from joining or rejoining the workforce. In fact, 28% to 40% of parents surveyed for the U.S. Chamber of Commerce Foundation’s 2021 Untapped Potential research said they, or someone in their household, did not take a job or had to change jobs due to issues with finding suitable child care.
In turn, the data indicates, businesses’ ability to recruit and retain qualified workers is diminished.
Status quo means states lose $2.7B
We cannot continue with the status quo, because when child care breaks down, everyone suffers. The Chamber Foundation research found that states lose an average of $2.7 billion annually due to gaps in child care. This figure includes an average of $528 million in lost tax revenue and $2 billion lost from employee turnover and absences.
The data is clear: Child care is a workforce issue.
Determine employees’ child care needs
Employers can take steps to improve child care access for employees, families and — most important — children.
First, ask employees what they need. While business owners may think they know their workforce well, there is no substitute for real conversations around employees’ experiences.It’s important to remember that no two families are the same when it comes to taking care of their children.
Create opportunities and safe spaces for communication that allow for honest feedback from employees. This isthe easiest and most effective way to begin to address the challenge of child care gaps.
Build in flexibility
Often, flexibility is the biggest variable in parents’ ability to find suitable child care. Business owners can’t always directly change how accessible child care is, but they can work with their employees on adjustments, such as providing flexible hours, shifts or schedules.
Employers also can leverage the growing trend of hybrid work.
All industries and regions are feeling the ramifications as families across the country struggle to find access to quality, affordable and flexible care for their children.
Ultimately, the best solutions will come from different stakeholders working together. The business community is well-positioned to take a leadership role in their employees’ ability to access child care effectively. A proactive and collaborative solution to fixing the child care crisis in America will yield returns for the economy, parents’ quality of life and our children’s educational future.
(Bloomberg) -- Singapore’s two largest new-economy firms have been touted as the next big thing for years. A $71 billion rout in their share prices in 2022 seems to show investors aren’t buying the story.
Shares of ride-hailing company Grab Holdings Ltd. have more than halved since the start of the year while gaming and e-commerce giant Sea Ltd.’s stock price has tumbled by 46%. The two U.S.-listed firms are languishing at the bottom of the MSCI Asean Index, with Grab among the biggest losers on the Asia Pacific stock benchmark as well.
The slump comes months after MSCI Inc. added the shares to its indexes amid much fanfare as it sought to give its regional gauges more exposure to new economy stocks. The tech selloff and waning global interest in special purpose acquisition companies have taken a toll on the firms.
“Passive investors would have lost a fair bit of money on these stocks,” said Brian Freitas, an analyst who publishes research on independent research website Smartkarma. Future price action “depends on how the companies perform and the global macro environment -- neither of which look terribly encouraging at the moment.”
Grab was added to the MSCI Asean Index in February, hot on the heels of its merger with blank-check company Altimeter Growth Corp. Sea’s inclusion in the gauge began in May last year.
Freitas estimates that passive holdings of Sea and Grab are close to $2.8 billion and $280 million, respectively. The stocks have lost a combined $71 billion in market value this year.
Judging by the earnings outlook, there may be little respite in store. Sea, which counts Chinese social media leader Tencent Holdings Ltd. as its biggest shareholder, is betting on growth at its online retail unit Shopee as its gaming arm faces slower bookings. But, Sea shut its main e-commerce operation in India on March 29, soon after the country banned its marquee flagship game Free Fire along with dozens of apps it says are of Chinese origin, citing security concerns.
“Shopee’s growth trajectory is flattening rapidly alongside India and France exits,” said Oshadhi Kumarasiri, an equity analyst with LightStream Research. “For a company priced expensively based on its future growth, it’s difficult to brush off the impact of an exit from a huge market like India. The growth story of Sea is falling apart.”
Meanwhile, Grab’s losses are mounting and the firm continues to splurge on subsidies.
Still, analysts have been slow to cut target prices given the two companies’ status as market leaders in Southeast Asia. They expect a return of at least 68% on both stocks over the next 12 months, according to data compiled by Bloomberg.
(Bloomberg) — The Reserve Bank of Australia is under pressure to begin tightening monetary policy in as little as two months as a a strengthening economy together with pre-election budget spending fuels inflation concerns.
A number of economists have either brought forward their call for the first interest-rate rise to June or are highlighting risks from Governor Philip Lowe turning hawkish following the March 29 budget and amid rising global prices, a Bloomberg survey showed. All expect the cash rate to stay at 0.1% at Tuesday’s meeting, the first for newly appointed Deputy Governor Michele Bullock.
Advertisement 2
Article content
The RBA will be keen to stay out of the political spotlight given an election is due in May, even as the labor market approaches full employment and job vacancies hit a record, consumer spending is strong and commodity prices soar after Russia’s invasion of Ukraine. Indeed, core inflation is already above the midpoint of central bank’s 2-3% target for the first time since 2014.
Normally, that combination would trigger a rate hike from the RBA, as it has in global counterparts in the U.K., U.S., Canada and New Zealand. But beyond the election campaign, Lowe remains doubtful that higher inflation is sustainable without stronger wages growth. He wants to see salary increases of 3% or more, compared with the most recent reading of 2.3%.
Advertisement 3
Article content
At the same time, Russia’s war on Ukraine has added psychology to the consumer-price equation, with households hit by soaring gasoline prices lifting inflation expectations. Lowe worries those perceptions will make higher inflation a reality, and he needs to guard against that. Government budget cash handouts and fuel tax cuts only add to the mix.
What Bloomberg Economics Says…
“With price pressures remaining elevated due to the conflict in Ukraine, the RBA is likely to move sooner instead of later.”
— James McIntyre, Economist.
Read the full report here.
Money markets expect the RBA to join the ranks of the Federal Reserve and the Bank of England by hiking in June. The cash rate is then seen climbing to 2.2% in a year’s time and 3.3% in two years. The median estimate of economists has come forward to July — due to some advancing their calls to June from August.
Advertisement 4
Article content
Recent stimulus measures, “raise the prospects that the budget could lead to higher inflation,” said Josh Williamson, chief economist for Australia and New Zealand at Citibank Inc. “Consequently, this also raises the risk of a more hawkish RBA.”
A rate rise in June would mean the election was out of the way and give Lowe a chance to review first-quarter inflation and wages readings on April 27 and May 18, respectively.
While Lowe’s reference to inflation psychology last month signaled a softening of his stance, he remains among the most dovish central bankers in the developed world. The governor maintains that Australia, which doesn’t have the intensity of inflation pressures of the U.S. and U.K., can afford to hold off hiking and test how low it can drive unemployment before wages accelerate.
“There’s a huge benefit to the country of having people in jobs,” Lowe told journalists two weeks ago. “While we can, we’ll keep interest rates very stimulatory to get people back into jobs. And how long we can do that for? I’m not sure, but that’s a priority at the moment.”
(Bloomberg) -- French voters will decide this month if they want to give Emmanuel Macron another chance to overhaul the country’s economic and social fundamentals.
The independent centrist won over the French in 2017 with promises to improve the business environment with tax cuts and encourage work with changes to labor and welfare laws. But after a flurry of action in the first year of his presidency, that reform drive was slowed by the Yellow Vests movement and brought to a halt by the Covid pandemic.
Pollsters predict that after winning the first round April 10, Macron will likely face and beat nationalist candidate Marine Le Pen in the second round April 24. If they’re right, then these are the key policies that will shape France for the next five years — bearing in mind the war in Ukraine casts a shadow over the feasibility of some of his plans.
Fiscal Policy
► Taxes
The French leader says he would continue cutting tax rates to drive economic activity and lighten the fiscal burden on labor.
For businesses, he plans further cuts to levies on production and lower charges for the self-employed. For households, he pledges to abolish the television license fee and raise the ceiling for tax-free inheritance.
The cuts would cost the state a total of 15 billion euros ($16.5 billion) once fully implemented.
► Spending
Macron plans to set aside 10 billion euros for the green transition, which would include renovating buildings, subsidies on electric vehicles and planting trees. Education and health are also in line to get a boost from public investment.
Combined with the tax cuts, the total cost of Macron’s program would reach 50 billion euros a year by the end of a five year term in 2027.► FinancesTo foot the bill, Macron says he has lined up the equivalent amount of cost savings. In the manifesto, there is little detail on specific measures under the broad headings of modernizing the state, cutting operating costs and curbing local authority spending.
Overall, Macron’s team says the budget deficit would still fall below 3% of economic output by 2027, in line the forecasts of his current government. The plan is based on optimistic assumptions on growth and the impact of reforms on the country’s growth potential in the long run.
Social Policy
► Labor
Macron is sticking to the mantra that guided economic policy making during his first term: make work pay. Some measures could prove popular, such as tripling the tax-free allowance for bonuses he introduced during the Yellow Vests protests, guaranteeing a childcare solution for all, bolstering profit-sharing mechanisms, or introducing more flexibility on vacation days.
Beyond those carrots to make work more attractive, there are also sticks that may prove red flags to France’s labor unions. Macron says he would add conditions to the minimum level of welfare and vary the generosity of unemployment insurance according to the strength of the job market.
According to the manifesto, the changes would drive unemployment down to 5% — a level not seen since the end of the 1970s.
► Health
Macron wants to incentivize the production of medicine in France, after facing shortages during the Covid crisis, and organize a conference on how to make sure there are no “medical deserts,” areas without any doctors.
To boost the quality of life of older people, he wants to recruit retirees to give their time in a variety of areas, from helping children with homework to advising entrepreneurs. He also pledges to set aside 1,100 euros a month as the floor for pensions for those who have worked their all their lives. Following reports of mistreatment in care homes, he plans to recruit more carers.
► Pensions
When Covid plunged France into recession in 2020, Macron hit pause on his plans to overhaul pensions. The key difference in his new proposal is a clear pledge to raise the retirement age to 65 from 62 — something he’d excluded in his 2017 manifesto — rather than focusing on abolishing a multitude of sector-specific rules to create a single system. While he still aims for some simplification, the new plan no longer focuses solely on the unpopular idea of abolishing a multitude of sector-specific rules and advantages.
The changes he proposes would do a lot of the heavy lifting for the rest of his economic framework by increasing revenues for the state, reducing spending and boosting the country’s growth potential.
► Education
Of the 12 billion euro investment for education, half of that sum would go to increasing teacher pay for those starting their careers and those willing to change how and where they work. Schools would also get more organizational autonomy and greater power over hiring.
Climate
Macron has made a clear commitment to nuclear power with a pledge to build six next-generation reactors. He also promises a 10-fold increase in solar power and the construction of 50 offshore wind turbines between now and 2050. That could involve the state taking over some of the assets of Electricite de France SA, Macron has said.
The manifesto also sets out regulations to improve carbon-footprint labeling of consumer goods and an obligation to tie executive pay to their company’s social and environmental objectives. Macron wants to renovate at least 700,000 homes a year to help cut energy consumption.
Security and Defense
Macron plans to continue bolstering on-the-ground policing with 200 new gendarme brigades in rural areas and action forces including teachers and magistrates for the poorest suburbs. To combat cyber-crime, the state would hire 1,200 specialists and create filters to warn internet users.
To maintain military spending at 2% of economic output, he has outlined a plan to modernize the army with more jets, nuclear powered submarines, and armored vehicles.
Macron has pledged to “keep fighting radical Islam” by closing some mosques that don’t adhere to a charter on accepted behavior as well as expelling preachers and closing schools. He also wants to create a new border force and speed up the process for deporting people in the country illegally.
Foreign Affairs
Macron is adopting the pro-European Union stance that proved successful in the 2017 run-off against Le Pen.
In the name of strategic autonomy, he is calling for the EU to massively increase its defense capabilities and coordinate its national armies. He seeks to build a European version of the metaverse, a network of virtual, 3D worlds that U.S.-based Meta is working on.
Macron has made clear that Europe should keep the economic pressure on Russia following the war in Ukraine while avoiding verbal escalation against Vladimir Putin to keep all channels open for discussion. He also wants the bloc to move away from Russian oil and gas in the long term, and welcome a share of Ukrainian refugees.
Read more: France’s Stunning Economic Rebound May Seal Macron’s Re-ElectionHow Macron’s Campaign Got a Boost From Ukraine War: QuickTake
America, I’m afraid to report, teeters on the precipice of inexorable decline. Our once limitless horizon is suddenly contracting, our outlook increasingly grim. Ross Douthat, The New York Times’ preeminent moral handwringer, lives in fear of the “stagnation, loneliness, alienation” our future has in store.1
The cause for all this doomsaying? Not heat waves, wildfires, floods, or any of the other manifestations of the climate crisis. No, far more concerning for those in the halls of power is the 2020 census, which found that the US population is growing at a slower rate than at any time since the Great Depression. Fifty years ago, fears ran rampant that the “population bomb” announced by biologists Paul and Anne Ehrlich would produce a world without enough space to feed its untold billions of inhabitants. Now it’s a population “bust” we must prevent, what political scientist Darrell Bricker and journalist John Ibbitson describe as “a relentless, generation-after-generation culling of the human herd” in their 2019 manifesto Empty Planet. While the demographic slowdown that might produce this frightful culling is currently limited to the United States, Europe, and East Asia, Bricker and Ibbitson argue that even South Asia and sub-Saharan Africa—the regions whose growth most terrified the Ehrlichs in the ’70s—will see their populations peak by mid-century.2
For many economists, the coming demographic apocalypse is a problem only insofar as it will damage the gross domestic product. Though the GDP does not speak in any meaningful way to people’s actual quality of life, it remains an obsession of policy-makers around the world, who accept the premise that a growing GDP is a sign of a healthy economy and that a rising population is a key component of that equation. In a March working paper, Charles Jones, a professor of economics at Stanford University, wrote, “When population growth is negative…living standards stagnate for a population that gradually vanishes.” Conversely, “an ever-increasing population benefits from ever-rising living standards.” As is typical in mainline economics, “living standards” here are defined by GDP per capita, the number you get when you divide a country’s gross domestic product by its population.3
By this metric, life in America has never been better. GDP per capita is over $59,000, more than twice what the country enjoyed in 1980. But by most other measures—not the least of which is common sense—it has only gotten harder for Americans to prosper over the past half-century. The federal minimum wage has lost more than a third of its value since the late ’60s, while the rising cost of housing regularly outpaces both inflation and wage growth, as does the price of health care and college tuition.4
Making matters worse, the United States has emitted 300 billion tons of greenhouse gases over the same period, and average temperatures here last summer were up 2.6 degrees Fahrenheit. With each passing year, the climate crisis ravages a different population—fires burning down homes in the Sierra Nevada, rainstorms flooding basement apartments in Queens, heat waves broiling the Pacific Northwest. When so many Americans find it difficult to get by and are gripped by encroaching fears of climate disaster, is it any surprise that they aren’t rushing to become parents?5
Pronatalists like Douthat are hardly interested in addressing rising living costs or climate change, given their devotion to liberal orthodoxy. In an essay last spring titled “How Does a Baby Bust End?,” Douthat suggested that pairing European-style parental benefits with a rising GDP might do the trick. “Call this the Joe Biden-baby-boom hypothesis,” he wrote. “If you spend on family benefits and run the economy hot enough, maybe fertility rates will finally begin to float back up.” To put it more simply: The solution to the thing preventing growth is more growth.6
There is, however, an alternative economic model to look to, one that sidesteps the growth paradigm and focuses on creating an ecologically sustainable country that might actually give its residents a shot at a decent life.7
The contemporary degrowth movement owes much of its intellectual foundation to the Club of Rome’s pathbreaking work. Composed of 16 academics from the United States, Europe, India, and the Middle East, the Club of Rome released The Limits to Growth in 1972, a report arguing that ever-increasing population and capital would create “negative feedback loops” that would eventually compromise both. Of the several loops the authors detailed, pollution and the depletion of nonrenewable resources posed the greatest risk to humanity. “The delays inherent in the action of these negative loops tend to allow population and capital to overshoot their ultimately sustainable levels,” they wrote. “The period of overshoot is wasteful of resources. It generally decreases the carrying capacity of the environment as well, intensifying the eventual decline in population and capital.”8
This school of thought came back into vogue in the years after the Great Recession, when GDP was bouncing back while real wages remained stagnant. Proponents of degrowth hold that conventional economics needs to be abandoned in favor of a system that prioritizes the eradication of disparities in wealth and a rollback of carbon capitalism. While the authors of Empty Planet contend that the earth is approaching a population tipping point, after which global deaths will outpace global births to disastrous economic effect, degrowthers argue that this dynamic is unfolding already, as the climate crisis indicates the global economy has overshot its ecological limits and needs to contract to a sustainable level. In their view, old arguments about population control are irrelevant: Since the population is already shrinking, degrowthers want to push legislators to embrace the decline and redirect their economies away from the market imperatives that are ravaging the environment.9
Tim Jackson is something of a pied piper for the movement. An ecological economist at the University of Surrey in England, Jackson wrote the degrowth handbook Prosperity Without Growth in 2009, as well as last year’s Post Growth: Life After Capitalism. Jackson told me that the alarm over the United States’ baby bust was symptomatic of the nation’s untenable fetishization of economic expansion. “The growth imperative and the population imperative go together,” he said. “Ultimately, I think we need to be working our way to a state of stable population.”10
While government-subsidized child care and generous parental leave are worthwhile progressive goals, the adoption of these policies in Japan and across Western Europe has done little to reverse declining birth rates. Instead, Jackson and other degrowthers offer a forward-looking solution: Accept that people don’t want to have as many children as they once did and think about the baby bust as a step toward a more sustainable economy. If the graphs of birth rates in most countries already show a clear inflection point, why not seize the moment and create a similar inflection point when it comes to economic production? As Jackson put it in his first book: “Our technologies, our economy, and our social aspirations are all badly misaligned with any meaningful expression of prosperity.” It’s time to try something new.11
While some have accused the Club of Rome of playing into the racist fearmongering about overpopulation that the Ehrlichs stoked in The Population Bomb (such as when they described a slum in Delhi as having a “hellish aspect”), today’s degrowthers don’t see the demographic rise of the Global South as a trend to be stopped. They argue that as the poorest nations begin to attain the standards of living currently enjoyed in the Global North, their populations will also stabilize, at which point the global economy can shrink to an ecologically sustainable level.12
When I e-mailed Samuel Alexander, a lecturer and researcher at the University of Melbourne, to ask about the economic pain a degrowth policy might entail for industrialized nations in the near future, he responded: “Given that billions around the world still live in conditions of material destitution, they have every right to increase their material living standards in sustainable ways. This makes it an ecological imperative that the high-impact economies (like the US and Australia, and those in Western Europe) reduce their impacts.”13
Of course, convincing the hundreds of millions of people in wealthy countries that they should accept a stagnant standard of living, however elevated, presents a herculean political challenge. Complicating matters are the doubts among many leftists that a degrowth world would be the idyll its proponents suggest. British journalist Leigh Phillips derided the program in a 2019 essay, “The Degrowth Delusion,” which argued that the most practical socialist alternative to free-market capitalism is for the government to assume control of the existing economic levers. “Let’s take over the machine, not turn it off!” he writes. In Phillips’s view, “degrowth unwittingly endorses what would be an imposition of austerity on the Western working class far beyond anything a Thatcher, Cameron, or May could imagine, this time in the name of the planet.” Yet while Phillips casts the degrowthers as the modern heirs to overpopulation alarmism, his critique fails to contend with the trends articulated in Empty Planet and instead takes an ever-increasing population for granted.14
The mere mention of the word “austerity” is enough to cool the blood of any committed leftist. But as Jackson demonstrates in Prosperity Without Growth, there’s little reason to be satisfied with the diminishing returns that the Global North sees from its focus on growth when compared with developing nations. Using political scientist Ronald Inglehart’s measure of “subjective well-being,” or SWB, as a proxy for life satisfaction, Jackson shows that as GDP per capita rises, SWB increases steeply for countries whose income is below about $15,000 per capita. The gains taper off as you move up the income spectrum, though, before flatlining at around $25,000—less than half of the United States’ current GDP per capita.15
The explanation for how GDP per capita could become so inflated without any significant gains in well-being? Consumerism. While replacing your laptop or trading in your sedan for an SUV does a wonderful job of stoking GDP growth, neither has much of an effect on your overall quality of life, and both are made possible only because of the labor of lithium miners and assembly-plant workers overseas. In conventional terms, this is a sign of a healthy globalized economy, as it means that countries like Vietnam and Panama are growing at the same time Denmark and Canada are. In ecological terms, though, the system requires ever more resource extraction and a nightmarishly complex maritime shipping network, which emits more greenhouse gases than commercial aviation.16
Rather than entertain a pullback from consumerism, liberals in North America and Western Europe have embraced so-called green growth, believing reforms like the Green New Deal will allow the world to avoid the worst excesses of climate change without fundamentally altering capitalism. The biggest issue with these initiatives is their time scale: Gentle market interventions may put the economy on a more sustainable course, but they’re unlikely to act quickly enough to decouple emissions from GDP growth at the rate necessary to seriously impede climate change. Giorgos Kallis, an ecological economist at the Universitat Autònoma de Barcelona, warns that even the most ambitious reforms being floated today will not prove sufficient in the long term. “The Green New Deal is the best proposal out there for moving us in the right direction,” he said. “But when people put numbers to it—a Green New Deal with the economy growing at 3 percent—it’s like running up a down escalator. You cannot [sufficiently reduce emissions] with the economy growing so fast.”17
The efforts of the city of Phoenix to draw down its water use while also growing at a rapid pace provide a clear illustration of Kallis’s point. In 2019, Kathryn Sorensen, then the director of Phoenix Water Services, bragged about her agency’s success in reducing residential water use when she told a journal published by the Yale School of the Environment, “We’ve decoupled growth from water…. We use the same amount of water that we did 20 years ago, but have added 400,000 more people.” This is a remarkable achievement, but one undercut by the fact that maintaining the same level of water use is itself unsustainable, given that the two decades Sorensen is referring to coincided with a megadrought that has left the city’s reservoirs with less water than at any time since they were first filled.18
The idea of running up the down escalator only grows more foolish when you consider the long horizon over which many decarbonization efforts are taking place. Many large companies, including major polluters like American Airlines and Ford, have committed to becoming “net zero” by 2050, a date that allows them to continue fouling the atmosphere under the assumption that new technology will come along in the next 30 years that will make it possible for them to simply remove as much carbon as they’re emitting. Even fast-tracked plans, like the Australian mining concern Fortescue’s bid to become fully green by 2030, still mean another decade of emissions from a company that currently burns 185 million gallons of diesel a year.19
Embracing degrowth might mean that a company like Fortescue will have to suspend operations until it can resume work in a sustainable manner, or that a city like Phoenix will have to limit the number of new homes to those it can realistically supply with water over the next century. Both are tough sells in a status quo that demands year-over-year growth no matter what, but such measures are becoming increasingly necessary as the window for avoiding catastrophic climate change closes.20
Putting any of this into effect would of course require a much stronger regulatory state. But look no further than Texas’s disastrous experiment in letting the utility market run wild to see how untenable the conservative preoccupation with deregulation has already become. When then-Governor George W. Bush signed the legislation creating the state’s free market for power in 1999, he promised, “Competition in the electric industry will benefit Texans by reducing monthly rates and offering consumers more choices.” By 2012, analysts were estimating that the new market had instead passed $22 billion in new costs along to consumers. The situation became disastrous last winter, when a cold snap sent rates soaring as much as 7,400 percent and left customers with electric bills as high as $17,000. As Kallis observed, “The government can stay out, deregulate things, and then what will happen? In 20 or 30 years, you’re just going to have heat waves, fires destroying economies everywhere. What would be efficient about that?”21
A more muscular government that would prevent such free-market failures could also implement what Alexander calls policies that “directly redistribute wealth, policies that ensure a dignified material baseline for all people, and policies that structure the economy in ways that ensure corrosive and undemocratic inequalities of wealth do not arise in the first place.”22
A population that isn’t constantly increasing may translate into a lack of economic growth, but what a focus on those metrics misses is the fact that the United States is already fabulously wealthy. Rather than continue waiting around for the über-rich to voluntarily share their spoils, it’s past time to radically redistribute the gains that have accumulated at the top to allow everyone at the bottom a baseline level of prosperity.23
Jackson calls policy-makers’ inability to think beyond the growth paradigm an “ideological straitjacket,” but he’s been encouraged by how their responses to the pandemic, as well as to the 2008 financial crisis, point toward a possible future in which the focus shifts from maintaining growth to taking care of people. “It turned out the government had the ability to protect livelihoods, build hospitals, intervene in supply chains, stimulate local community-based initiatives, and, indeed, find the financial wherewithal to do that out of nowhere, overnight,” he said. “It was an example of the sovereign power of government that capitalism had tended to deny, of the responsibility of government to intervene to protect the welfare of its citizens.”24
The early months of 2020, then, may be something of a blueprint for how a government can reform in response to an emergency. Lawmakers intentionally torpedoed the US economy in the name of public health, but the 30 percent plunge in the GDP was paired with experiments in providing a universal basic income and the transition of white-collar work into virtual space. It took a crisis to make such reforms possible. For lasting changes to be implemented, though, we need to recognize that the greatest challenge the country faces is not future demographic decline but rather the carbon capitalism that has prevailed for the past two centuries. “There was a sense during the pandemic that the ideology of capitalism could be put to one side,” Jackson said. “The fact we did it under extreme circumstances suggests we could do it under any circumstances.”25
Mexico’s government forecast economic growth of 3.4% for 2022, far below what the nation’s President was aiming for, a finance ministry document showed on Friday, as Latin America’s second-largest economy claws back losses from the COVID-19 pandemic.
The ministry said in a published budget document that it expects the economy to expand by 3.5% in 2023.
“The persistent impacts of the pandemic on supply and demand imbalances, and the escalation of the geopolitical conflict between Russia and Ukraine, have forced countries to adjust their growth expectations for this year,” the document says.
Article content
The new figure compares to President Andres Manuel Lopez Obrador’s projection of 5% growth for the economy in 2022 and a prior government forecast for a 4.1% expansion.
The budget document projected inflation at 5.5% by the end of 2022, slowing to 3.3% by the end of 2023.
The exchange rate is seen at 20.7 pesos per U.S dollar for the end of 2022, and 20.9 pesos at the end of 2023, the ministry said, compared with 19.8 pesos on Friday.
Mexico expects this year’s average oil price will be $92.90 per barrel, while crude production is estimated at 1.82 million barrels per day (bpd), rising to 1.85 million bpd in 2023.
The ministry expects an average of 879,000 bpd of crude exports in 2022.
The country will remain focused on promoting economic development and job creation through public spending, the document said, adding spending would not “jeopardize the continuation and completion of key infrastructure works or priority social programs.” (Reporting by Carolina Pulice and Anthony Esposito; Editing by David Alire Garcia and William Mallard)